


Interest rates affect far more than mortgage repayments. Learn how a prolonged period of higher rates could impact your investments, retirement plans, property and long-term financial strategy.
For much of the past two decades, Australians have become accustomed to relatively low interest rates. Borrowing was affordable, property values generally rose, and investors often had little choice but to move beyond cash to generate meaningful returns.
However, the economic environment has changed.
While many people continue to speculate about when interest rates may fall, there is another possibility worth considering: what if rates remain higher for longer?
If that occurs, the impacts will extend far beyond mortgage repayments. Interest rates influence everything from investment markets and property values to retirement planning and business decisions.
The good news is that higher interest rates don't create only challenges. For some, there may also be opportunities.
Why Are Interest Rates So Important?
Interest rates are one of the Reserve Bank's primary tools for managing inflation and supporting economic stability.
When rates rise, borrowing becomes more expensive. This can reduce spending across the economy and help bring inflation under control.
When rates fall, borrowing becomes cheaper, encouraging spending, investment and economic growth.
These movements influence a wide range of financial decisions, which is why interest rates are often described as the heartbeat of the economy.
The Impact on Borrowers
For homeowners and businesses carrying debt, higher rates can place pressure on cash flow.
Mortgage repayments may remain elevated, reducing the amount available for discretionary spending, investing or saving. Business owners may experience higher borrowing costs, affecting profitability and expansion plans.
While many borrowers have already adjusted to a higher-rate environment, prolonged pressure can still present challenges, particularly when financial plans were originally built around lower borrowing costs.
This highlights the importance of ensuring debt strategies remain appropriate and sustainable over the long term.
The Impact on Savers
Not everyone views higher interest rates negatively.
For years, savers struggled to generate meaningful returns from cash accounts and term deposits. Today, higher rates have improved income opportunities for many Australians holding cash reserves.
Retirees in particular may appreciate receiving stronger interest income on funds set aside for short-term spending needs or emergency reserves.
However, there is a potential trap.
While attractive interest rates can make cash feel safer and more rewarding, inflation may still erode purchasing power over time. Cash remains an important part of any financial strategy, but it may not always provide sufficient long-term growth on its own.
What About Property?
Property markets often feel the effects of interest rate changes relatively quickly.
Higher borrowing costs can reduce purchasing power and affect housing affordability, particularly for first-home buyers and investors.
At the same time, real estate markets are influenced by many factors beyond interest rates alone, including population growth, housing supply, employment levels and local economic conditions.
History has shown that property markets can remain surprisingly resilient even during periods of higher interest rates, provided broader economic conditions remain supportive.
What Does It Mean for Investors?
Share markets don't always react to interest rates in a straightforward way.
Higher rates can place pressure on company profits, increase financing costs and reduce consumer spending. On the other hand, many businesses are capable of adapting and continuing to grow in changing economic environments.
Importantly, investors who focus solely on interest rate headlines can sometimes lose sight of their long-term objectives.
Markets have navigated many different rate cycles throughout history. While periods of uncertainty can create volatility, disciplined investors who maintain a diversified strategy are often better placed than those attempting to predict every interest rate move.
The Retirement Perspective
For retirees and those approaching retirement, higher interest rates create a unique balancing act.
On one hand, stronger returns from cash and term deposits may help support short-term income needs.
On the other hand, retirement can span 20, 30 or even 40 years. Maintaining purchasing power throughout that period typically requires some exposure to growth assets such as shares and property.
The challenge is finding the right balance between generating income today and preserving wealth for tomorrow.
A retirement strategy built solely around cash may feel comfortable in the short term but could struggle to keep pace with inflation over the long run.
Opportunities Often Come From Change
Periods of economic adjustment can create opportunities for those willing to review their financial arrangements.
Examples may include:
The most successful financial plans are rarely built around predicting exactly what interest rates will do next. Instead, they are designed to remain resilient across a range of possible outcomes.
Final Thoughts
No one knows with certainty where interest rates will be in six months, twelve months or several years' time. However, understanding how a prolonged period of higher rates could affect your financial position can help you make more informed decisions today.
Whether you're a homeowner, investor, business owner or retiree, the focus should remain on maintaining a strategy that is flexible, diversified and aligned with your long-term objectives.
After all, successful financial planning isn't about predicting the future. It's about being prepared for it.
Global central banks are tightening policy as rising bond yields and long-term fiscal pressures reshape the outlook for Australian investors, with implications for portfolio duration and diversification.
Proposed changes to discretionary trust taxation could affect Australian business owners, investors and family trusts from 2028. Learn what has been proposed, who may be impacted and the key considerations before taking action.
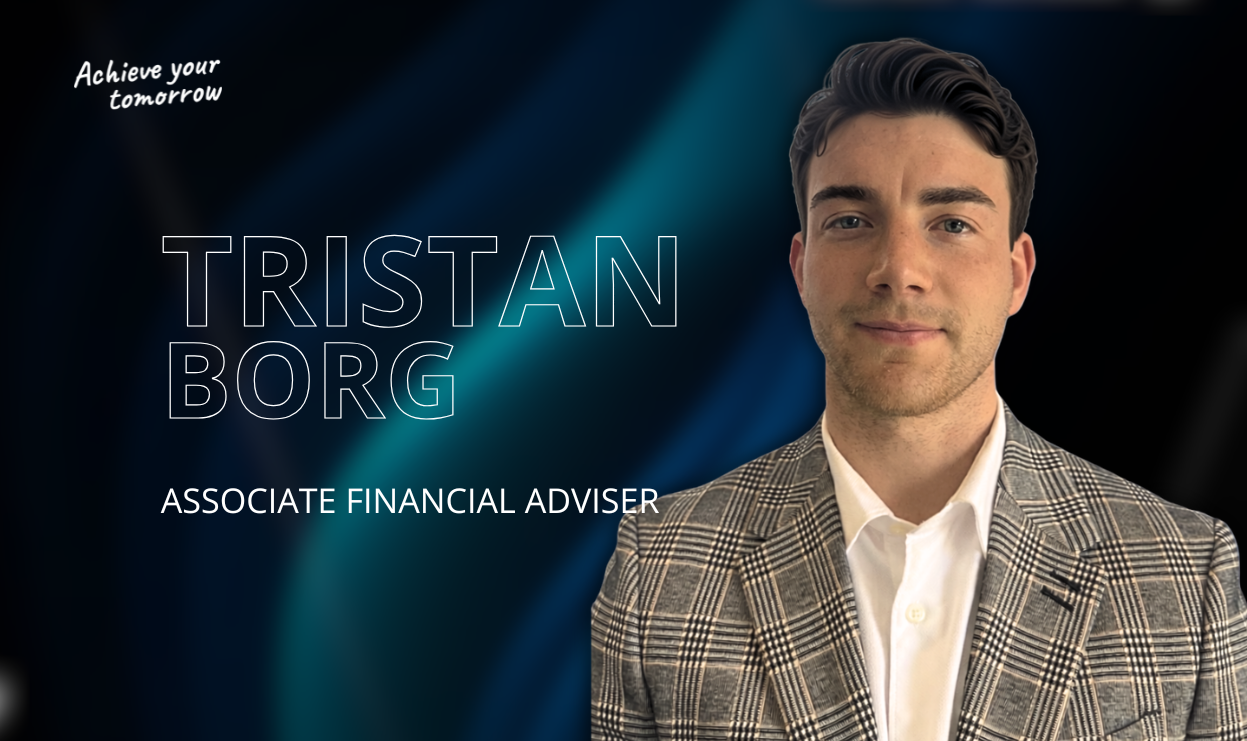
This edition’s Staff Spotlight gives us the opportunity to learn a little more about Tristan Borg, our Associate Financial Adviser based in our Beaumaris office.
Stay in the know with the latest updates, insights, and exclusive content delivered straight to your inbox.
